

Why European Universities Can't Rely on Traditional Recruitment Markets Anymore
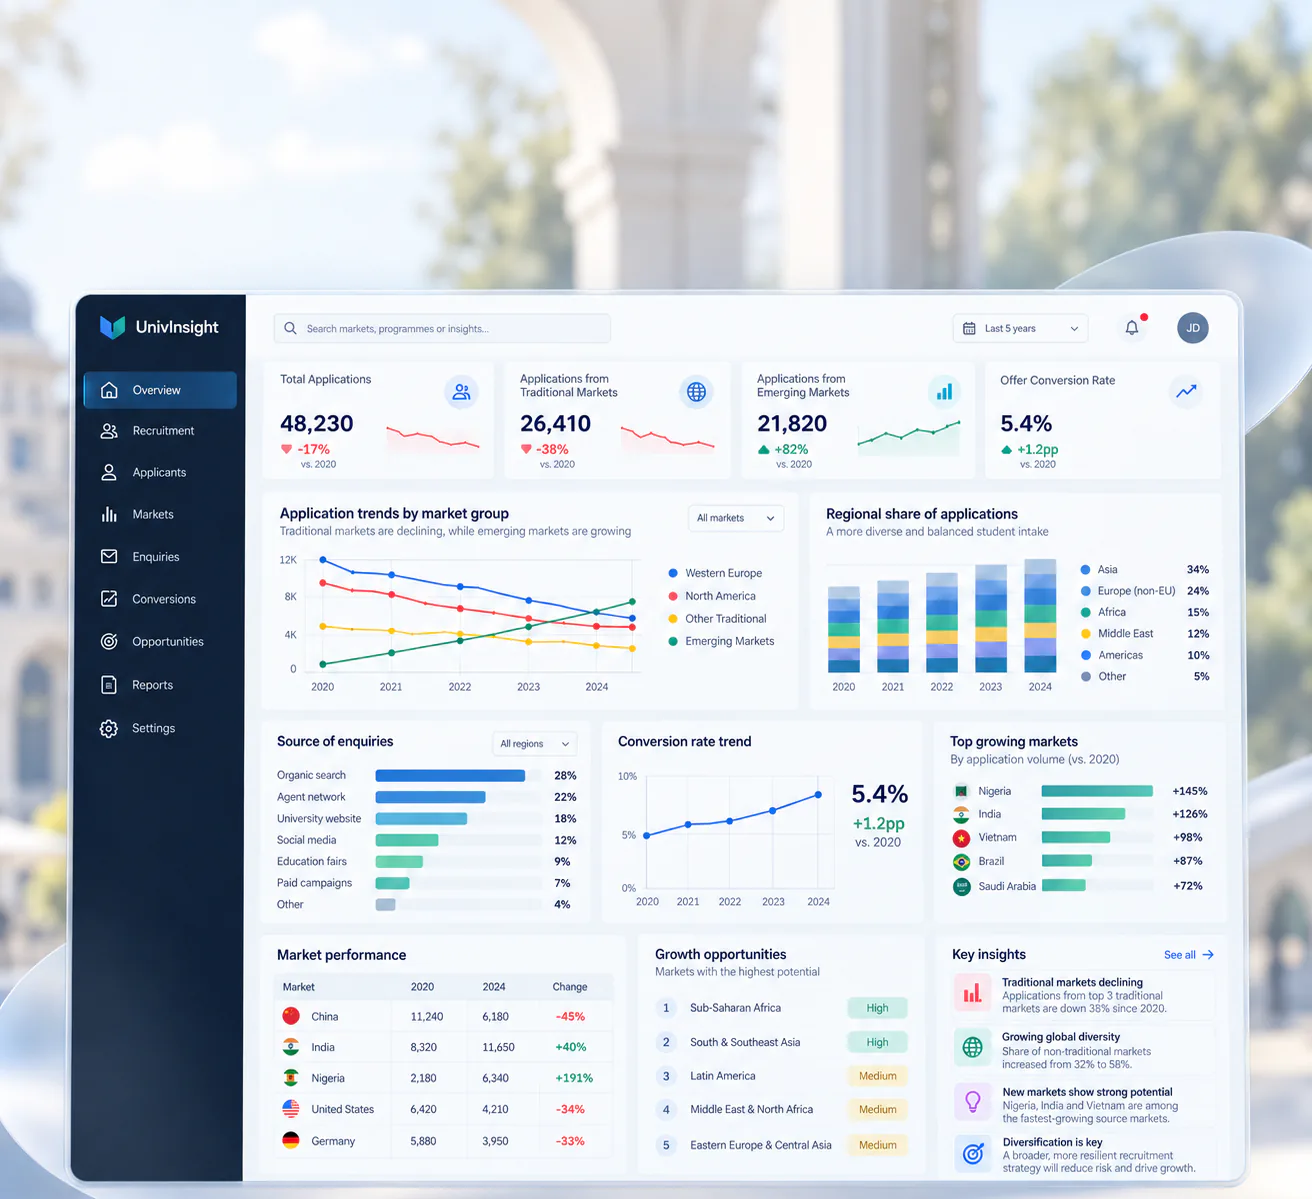
International student recruitment is becoming a concentration-risk problem
Many internationally active European universities and business schools have historically built recruitment around a relatively small number of dependable source countries. The names vary by institution, but the logic is the same: a handful of markets supply most of the pipeline, so most of the budget, staff time and agent relationships go there. While demand kept growing, that logic worked.
That concentration can now be a major structural weakness in an international recruitment strategy. European universities can no longer rely disproportionately on traditional recruitment markets because international student mobility is becoming less predictable and more sensitive to affordability, visa policy, domestic education capacity and competition from a much wider field of destinations. The evidence is not that demand has collapsed. OECD data shows that after three years of post-pandemic growth, new international student inflows to OECD countries fell by around 13% in 2024, with the decline concentrated in the United States, the United Kingdom, Canada and Australia, while inflows to the rest of the OECD grew by 5%. Student mobility is redistributing rather than disappearing.
To be precise about what the title means: "can't rely" does not mean traditional markets no longer matter. China and India remain by far the largest origin countries for internationally mobile students. "Can't rely" means an institution cannot safely assume that historical volumes from any single market will continue unchanged, and cannot let a disproportionate share of its international intake, or its international tuition income, depend on one or two countries whose demand can shift for reasons entirely outside the institution's control.
That is a concentration risk, and it deserves a working definition:
Recruitment concentration risk is an institution's exposure to enrolment or revenue disruption because too large a share of its international pipeline depends on a small number of source markets.
The resilient response is not to abandon established markets, and it is not to "recruit everywhere". It is to protect strong core markets while deliberately building a measured portfolio of growth and test markets, evaluated with full-funnel enrolment data rather than headline lead volume. This article explains what has changed, where new demand signals are appearing, how to assess whether a market deserves investment, and how to run diversification as an operational discipline rather than a slogan.
What counts as a traditional recruitment market?
There is no universal list of traditional markets, and treating the question globally hides the risk. A useful definition is institution-specific:
Traditional recruitment markets are the source countries on which an individual institution or national system has historically depended for a disproportionate share of its international enrolments.
One terminology point matters throughout this article. A source market is where prospective international students come from: India, China, Nigeria, Pakistan or Indonesia, for example. A destination market is where they choose to study: Germany, France, Spain, the Netherlands, the UK or Canada, among others. Both patterns are changing, but they are different trends. This article is primarily about European institutions diversifying their source markets; the changing destination landscape matters because it reshapes the competitive environment in which they recruit.
For many of the world's largest international education systems, China and India have been especially important sources. In 2023, Chinese and Indian students accounted for 17% and 14% respectively of all international students enrolled in OECD countries, roughly one-third combined, according to the OECD's International Migration Outlook 2025. But depending on the institution, programme and country, traditional markets can also include neighbouring European countries, particular linguistic or former colonial networks, specific Middle Eastern markets, North America, Southeast Asia or parts of Africa. A French grande école, a Dutch research university and a Portuguese business school will each have a different concentration profile.
The practical consequence is that market concentration should be assessed from the institution's own enrolment and revenue data, not from a generic sector list. The question is not "is China risky?" but "which markets does our intake, and our income, actually depend on, and how exposed are we if one of them softens?"
What has changed in international student mobility?
Global demand for international education remains very large. Students from Asia represented 58% of internationally mobile students across OECD countries in 2023, according to OECD Education at a Glance 2025. What has changed is not the scale of demand but its distribution, its drivers and its volatility.
The OECD's April 2026 report International Students in Higher Education, which compares Australia, Canada, France, Germany, the Netherlands and the United Kingdom, describes international student mobility as entering a more uncertain phase, with some countries tightening policy while others continue to expand international enrolment. The same report notes that international students' origins have become more concentrated over the past decade, with students from Asia making up a larger share of international enrolments in 2023 than in 2013 in Australia, Canada, Germany and the UK. Concentration, in other words, is a sector-wide pattern, not an individual institutional failing. That is exactly why it now carries system-level risk.
The table below summarises the main structural changes and what each means for a recruitment strategy.
| Structural change | Recruitment implication |
|---|---|
| New inflows to OECD countries fell around 13% in 2024, concentrated in the US, UK, Canada and Australia, while other OECD destinations grew (OECD, 2025) | Demand is redistributing, not disappearing. Plans built on uninterrupted growth from historical markets need scenario testing |
| Destination policy has become a live variable, with caps, financial thresholds and visa changes introduced at short notice in several major destinations | A market's viability can change mid-cycle for reasons outside the institution's control. Reassess markets every cycle |
| Students weigh affordability, living costs, work rights and return on investment more explicitly | Value, cost and career evidence must be communicated per market, not assumed |
| More destinations compete credibly for the same students, in Europe, Asia and the Middle East | European institutions inherit nothing automatically. Proposition and applicant experience decide outcomes |
| Domestic capacity and transnational education (TNE) give students international options closer to home | The competitor is no longer only another foreign university; sometimes it is an international programme at home |
| Discovery channels are fragmenting across AI-assisted research, social platforms, comparison sites and agents | Geographic diversification must be matched by channel diversification and source attribution |
China and India remain huge, but size does not remove volatility
Nothing in the current evidence supports a "China is declining" or "peak India" narrative, and this article does not make one. China and India remain the two largest origin countries for international students in OECD destinations. They remain strategically important across international higher education, although their importance varies substantially by institution, programme and destination country.
The point is subtler: dependence on either market is less safe than assuming historical volumes will continue indefinitely. In China's case, sector analysts, including the British Council over a number of years, have pointed to structural factors that shape long-run outbound demand: the continued expansion and improving quality of China's own higher education system, demographic change, economic conditions and graduate employment pressure, and a growing set of destination options within Asia. Current British Council analysis points to softer Chinese flows in some major destination markets alongside continued growth in regional and TNE alternatives. None of this makes China unimportant; it makes Chinese demand something to monitor and model rather than assume.
India illustrates volatility from the opposite direction. Outbound mobility from India grew extremely quickly after the pandemic, and destination policy changes then affected demand sharply and unevenly. UK data shows the pattern within a single system: HESA reported 685,565 students with a permanent address outside the UK in 2024/25, around 6% fewer than in 2023/24, with postgraduate taught enrolment particularly affected and entrant numbers from India, China and Nigeria declining, while enrolments from several other markets grew in the same year. Rapid growth can be followed by corrections; demand differs significantly by study level, discipline and region within India; and Indian students now have a wider range of credible destination choices than in the recent past. The lesson is that even very large markets can be volatile, not that institutions should recruit less in India.
Students have more destination choices
The historic dominance of the "Big Four" destinations, the United States, the United Kingdom, Australia and Canada, is loosening. In 2024 those four countries still accounted for 65% of international student inflows to the OECD, but all four saw year-on-year declines, the first such simultaneous drop since the pandemic, while inflows to other OECD destinations rose 5%, according to the OECD. Japan welcomed around 167,000 new international students in 2024, a 20% increase on the previous year, and Denmark, Korea, New Zealand and Sweden recorded some of the steepest rises among other destinations.
ICEF, in its 2026 Insights analysis, describes this as a shift from the Big Four towards a much broader field it calls the "Big Fourteen", a group including European destinations such as Spain, Italy, Germany and France alongside Asian destinations such as Malaysia, South Korea, Japan and Taiwan. The "Big 14" is sector shorthand rather than an official statistical classification, but the underlying pattern it describes is well documented: students, particularly those facing visa uncertainty or affordability pressure in traditional Anglophone destinations, are actively considering a wider set of countries, and many of those countries are recruiting more assertively than before.
Affordability and ROI matter more
Cost has moved to the centre of student decision-making. ICEF's Agent Voice survey, which collected responses from 1,225 education agents across 113 countries between April and September 2025, found that affordability and cost of living edged out visa issues as the top factor shaping students' study-abroad decisions, with both remaining critical, alongside employment opportunities. This is a survey of agent perceptions rather than a census of students, but agents sit close to demand and tend to see shifts early, and the finding is consistent with destination-level enrolment patterns. Students and families increasingly compare total cost, work rights, scholarships and likely career outcomes across destinations before committing. Full Fabric's research on what prospective international students are prioritising points in the same direction: employability, post-study pathways and clear cost information weigh heavily.
Currency movement adds a layer that institutions often overlook. A European degree can become materially more or less affordable for a given market without the institution changing a single fee, purely through exchange-rate shifts, local inflation or changes in families' access to international payment mechanisms. The operational implication is not financial forecasting; it is that market viability should be reassessed every recruitment cycle rather than fixed in a multi-year plan.
Regional study and TNE are growing alternatives
The final structural change is that the alternative to enrolling at a European campus is no longer always another foreign university. Students increasingly have options to obtain an international education closer to home, through regional destinations, branch campuses, joint programmes, transnational education and online or hybrid provision. The British Council's 2026 analysis highlights TNE as an increasingly important channel, including for students in China and South Asia who choose to stay in their home country while enrolling in a foreign institution's programme. Regional destination hubs in Asia and the Middle East are investing heavily in English-taught provision, scholarships and post-study pathways.
For European recruitment teams, this changes the competitive question. An institution is not only competing against peer universities abroad; in some markets it is competing against the option of not leaving at all.
Why Europe cannot assume displaced demand will come automatically
It is tempting to read the 2024 declines in the US, UK, Canada and Australia as a windfall for continental Europe. There is a real opportunity: European destinations may capture students who are reconsidering the traditional Anglophone options, and OECD data shows several European countries growing while the Big Four contracted. Germany was the only one of the six destinations in the OECD's 2026 comparative study to record continued growth in new international entrants, with a 9% increase in newly enrolled foreign students in the winter semester 2024/25.
But the opportunity comes with two hard caveats.
First, Europe is not one market. France, Germany, Spain, Italy, the Netherlands, Portugal, Finland, Switzerland and the UK differ substantially in tuition fees, visa processes, housing availability, work rights, language of instruction, programme portfolios and employability outcomes, and their policies are moving in different directions. The OECD notes that since 2024 Australia, Canada, the Netherlands and the UK have moved to stabilise international student numbers, while France and Germany have continued policies aimed at attracting more international students. The Netherlands, for instance, has seen sustained policy debate and institutional measures aimed at balancing internationalisation with Dutch-language provision. A prospective student comparing "Europe" is really comparing a set of very different national propositions, and an institution's recruitment message has to reflect the specific conditions of its own country and campus.
Second, displaced demand is contested demand. The same students European universities hope to attract are being courted by destinations across Asia and the Middle East that are affordable, increasingly well ranked and actively recruiting. Students who leave the Big Four consideration set do not default to Europe; they choose whichever destination offers the most convincing combination of programme fit, cost, visa certainty and career outcome. European institutions still need a strong proposition, accurate and localised information, a fast and humane applicant experience, and a recruitment operation that can follow up competently across time zones and languages. Institutions that treat the current moment as an automatic inheritance will be outcompeted by those that treat it as a contest.
Where new recruitment demand is emerging
The regions below show credible current demand signals. Two disciplines apply throughout. First, a signal is not an enrolment: search interest, visa issuance and survey responses measure different things, and none of them equals students arriving on campus. Second, none of these regions is one market. Country conditions differ sharply, and an institution's own data should decide where to invest.
South Asia beyond India
Current evidence points to broad-based demand growth across South Asia. The British Council's Five Trends analysis, published in early 2026, reports that UK student visa issuance to South Asian applicants rose sharply through 2025, with roughly 26,000 more visas issued in the first three quarters of 2025 than in the same period of 2024. Issuance to applicants from Bangladesh and Nepal roughly doubled year on year, and issuance to Pakistani applicants reached an all-time high. UK enrolment data shows the same direction: HESA reports that enrolments from Nepal rose 92% in 2024/25, while Pakistan continued its year-on-year growth, even as overall UK international enrolments fell.
Two cautions apply. Visa issuance measures permissions granted, not enrolments completed, and UK visa growth does not automatically translate into demand for any given institution elsewhere in Europe. What the data does support is the narrower conclusion that international demand within South Asia is considerably broader than India alone. Before investing, an institution should validate locally: does demand in Bangladesh, Nepal, Pakistan or Sri Lanka match its programme portfolio, price point, language of instruction and entry requirements, and can applicants realistically finance study and obtain visas for its country?
Southeast Asia
Southeast Asia combines large young populations with rising study-abroad aspiration. Studyportals reported in May 2026 that by early 2026 Indonesian students represented a larger share of global study-abroad interest on its platform than at any previous point in its dataset, with demand signals suggesting interest broadening beyond the traditional Anglophone destinations. That figure measures student search interest on the Studyportals platform, not enrolment, and it should be read as an early demand signal to validate rather than proof of future volume. Vietnam, Thailand and Indonesia also appear repeatedly among the regions institutions worldwide say they are targeting for diversification in Studyportals' Global Enrolment Benchmark Survey.
For European institutions the practical questions are programme fit (demand skews towards particular subjects and levels), affordability relative to regional alternatives such as Malaysia and Japan, and whether the institution can support applicants through documentation and payment processes from these markets.
Sub-Saharan Africa
Sub-Saharan Africa combines a young and growing population, rising tertiary participation demand, capacity constraints in domestic systems and strong aspiration towards international study. In Studyportals' Global Enrolment Benchmark Survey, based on responses from 461 institutions across 63 countries for the August to October 2025 intake, Sub-Saharan Africa, with Nigeria, Ghana and Kenya named most often, was among the regions institutions most frequently cited as diversification targets. That is a survey of institutional strategy, and it is evidence of where the sector is looking, not proof of future enrolment volume.
Affordability and currency exposure are real constraints, and they differ enormously by country. Nigeria, Ghana and Kenya have very different economic conditions, currencies, education systems, application patterns and visa outcomes, and demand from each behaves differently by programme and level. Treating "Africa" as a single market is an analytical error that leads directly to wasted budget. The region rewards institutions that pick specific countries, specific programmes and specific price points, and that measure conversion honestly, including visa-related attrition.
Other evidence-backed opportunities
Studyportals' benchmark survey also identifies Latin America and Gulf markets among the regions institutions are exploring for diversification. Both deserve consideration where an institution's own evidence supports it, with one shared caveat: Gulf countries are investing heavily in domestic provision and branch campuses, which makes the region a competitor as well as a source. Whether either region is attractive for a specific European university depends heavily on programme, price, language, scholarships, existing partnerships and the institution's own enquiry, application and alumni evidence.
What this article deliberately does not offer is a ranked list of "top emerging markets". The right market depends on the institution's programmes, qualification levels, languages, price point, brand strength, location, visa environment and alumni base. A market that is excellent for one business school's specialised master's programmes may be poor for another university's undergraduate humanities intake. The useful skill is not knowing a ranking; it is knowing how to evaluate.
Diversification does not mean recruiting everywhere
Diversification has a failure mode, and it is worth naming before building the framework: spreading a limited budget thinly across dozens of countries. "We recruit globally" is not a strategy. Thirty markets with no local relevance, no channel evidence and no follow-up capacity can produce worse outcomes than three well-understood markets, because every market carries fixed costs in content, compliance knowledge, agent management, communication timing and applicant support.
A good diversification strategy sounds different: a defined set of evidence-backed markets, each with clear programme fit, measurable acquisition channels, an owner and a defined investment level, reviewed every cycle. The goal is to reduce concentration risk without destroying focus. The sector is clearly moving in this direction: in the same Studyportals Global Enrolment Benchmark Survey of 461 institutions across 63 countries, roughly 40% of respondents reported plans to diversify recruitment into new markets, the most cited strategy among respondents in Canada, Europe, the US and the UK. That figure describes the institutions surveyed, not all universities globally, but the directional shift is clear. The differentiator will be who diversifies with discipline.
A practical source-market portfolio for universities
A useful way to bring discipline to diversification is to manage recruitment markets the way an investor manages a portfolio: different holdings, different roles, different levels of evidence and investment. The categories below are an editorial planning framework, not a formal industry standard, but they map cleanly onto how recruitment budgets actually get decided.
Core markets
Established markets with high volume, well-understood behaviour and predictable conversion. For many European institutions this includes China or India, and often neighbouring European countries. The strategy is to keep investing and keep measuring, while consciously monitoring exposure. Core markets are protected, not abandoned.
Growth markets
Markets where the institution's own evidence shows momentum: rising applications, improving conversion, good programme fit and external signals pointing the same way. These earn selective additional investment and channel coverage. Growth status is earned through full-funnel evidence, not sector headlines.
Test markets
Markets that look promising externally but where the institution has limited evidence of its own. These get modest budgets, controlled experiments, specific programmes and intakes, and a defined evaluation window. A test market is a question the institution is paying to answer, and the answer can legitimately be "no".
Partnership-led markets
Markets where relationships outperform broad paid marketing: education agents, partner schools and universities, pathway providers, TNE arrangements and alumni networks. International alumni deserve particular attention as credible, low-cost ambassadors; Full Fabric's guide to using alumni relations in international recruitment covers the practicalities.
A market can move between categories over time, and the same country can sit in different categories for different programmes. The portfolio is reviewed each cycle against enrolment outcomes, which is what makes it a management tool rather than a diagram.
How to decide whether a new recruitment market is worth entering
Whether a market deserves investment is a multi-dimensional judgement, and the dimensions below give recruitment leaders a repeatable way to make it. The unit of analysis matters as much as the dimensions: assess market × programme × intake, not country alone. A country is rarely "good" or "bad" for an institution as a whole; it is good or bad for specific programmes at specific levels in specific intakes.
| Dimension | What to measure | Why it matters |
|---|---|---|
| Demand | Historical enquiries and applications from the market, external mobility data, search and platform interest, local tertiary demand | Establishes whether interest exists at all, and whether it is growing or fading |
| Conversion | Progression from enquiry to application, submission, offer, acceptance, deposit and enrolment | Interest that never converts is a cost, not an opportunity |
| Programme fit | Which programmes, levels and subjects the demand attaches to, and whether applicants meet entry requirements | A market can be strong for one programme and irrelevant for another |
| Affordability | Tuition and living costs relative to local incomes, currency trends, scholarship availability, payment options | Affordability is now among the top decision factors students weigh |
| Visa and mobility environment | Visa process and documentation burden for the institution's country, approval reliability, post-study work rights | Visa friction suppresses conversion even among qualified, funded applicants |
| Competition | Which destinations and institutions target the same students, and on what proposition | Decides how hard-won each enrolment will be and what messaging must overcome |
| Recruitment infrastructure | Agents, schools, partners, alumni presence, digital channel viability, local representation | Determines whether the institution can actually reach and support applicants |
| Operational readiness | Language capability, communication timing across time zones, document handling, payment expectations | Weak operations quietly destroy conversion in otherwise promising markets |
| Concentration effect | How the market changes overall exposure: what happens to intake if it, or an existing core market, falls 20-30% | Diversification only works if the portfolio as a whole becomes more resilient |
The last dimension deserves emphasis, because it reframes the whole exercise. The most important operational question a recruitment leadership team can ask is: what happens to our intake, and our tuition income, if our largest market falls by 20-30% in one cycle? If the honest answer is "a budget crisis", the institution has a concentration problem regardless of how well its current markets are performing.
On thresholds: there is no recognised universal standard for how much concentration is "too much", and this article will not invent one. A postgraduate business school where one country supplies 30% of international students has a very different risk profile from a large public university with lower fee dependence. Instead of an arbitrary benchmark, institutions should model scenarios from their own data: what share of international enrolments comes from the top market and the top three; what proportion of international tuition revenue depends on them; which programmes are most exposed; what happens if applications from the largest market fall 20%, or if visa conversion deteriorates; and how quickly other markets could realistically compensate. The 20-30% figures used here are stress-test scenarios, not recommended concentration limits. Financial exposure matters as much as headcount exposure, and the two can diverge sharply where fee levels differ by programme.
Test demand before scaling investment
Between "this market looks interesting" and "this market gets a serious budget line" there should be a structured test. A workable five-stage process:
Stage 1: external evidence. Review mobility data, demographics, programme-level demand signals, affordability conditions and the competitive field. Sources such as the OECD, Eurostat, UNESCO, the British Council, Studyportals and ICEF each measure different things; use them for what they measure.
Stage 2: institutional evidence. Before spending anything, mine the institution's own data. Existing enquiries, historical applications, current students, alumni concentrations and partner relationships are the cheapest evidence available, and often reveal that a "new" market has been quietly applying for years.
Stage 3: small-market test. Design a controlled experiment: one or two specific programmes, a defined audience, a modest budget, one or two measurable channels, one intake. Set success criteria in advance, in funnel terms rather than lead volume.
Stage 4: full-funnel evaluation. Measure the test through application, offer, acceptance, deposit and enrolment, including cost per enrolled student, time to conversion and any visa-related attrition. A test that produces cheap enquiries and no enrolments has answered the question.
Stage 5: scale or stop. Increase investment only if the evidence supports it, and be willing to stop. A disciplined "no" after a small test is a success of the process, not a failure of the market team. Full Fabric's university student recruitment plan framework covers how market decisions connect to targets, budgets and calendars.
Measure markets by enrolments, not enquiries
The single most common analytical error in market diversification is judging markets by top-of-funnel volume. A market producing 10,000 low-intent leads can be strictly worse than one producing 800 highly qualified prospects, once conversion, acquisition cost and yield are counted.
A useful hierarchy separates what different data can actually tell you:
Signals. Search interest, platform demand data such as Studyportals interest metrics, event registrations and website traffic. Valuable for spotting change early, and nothing more.
Intent. Enquiries, brochure downloads, webinar attendance, programme comparisons. Stronger, because an identified person has acted, but still far from commitment.
Application behaviour. Applications started, applications submitted, documents completed. This is where seriousness becomes visible, and where markets begin to differentiate sharply.
Commercial and enrolment outcomes. Offers, acceptances, deposits and enrolments, and where relevant arrival and registration. This is the highest-value evidence, and the level at which market investment decisions should ultimately be made.
External signals earn attention; internal full-funnel evidence earns budget. In practice that means tracking, per market and per programme, the complete funnel from enquiry to enrolment, together with stage-to-stage conversion rates, acquisition cost, yield, revenue, time to conversion, and withdrawal, deferral and visa-related attrition where measurable.
Source attribution is the other half of measurement. Knowing which country a student came from is not the same as knowing which activity generated and influenced the enrolment: paid search, organic content, an event, an agent, a partner school, an alumni referral, a webinar, social, direct or an aggregator. Diversifying markets without source attribution simply spreads budget blindly across more geography. Agents deserve particular precision here: in many international markets they remain an important channel, and the right way to treat them is neither suspicion nor blind faith but measurement. Track each agent relationship's applications, offers, acceptances, enrolments, programme fit and geographic coverage, exactly as any other channel is tracked, and invest accordingly.
What market diversification changes operationally
Entering new markets is not only a marketing decision; it reshapes daily operations across the recruitment and admissions function.
Localisation, which is more than translation. Each market needs relevant messaging, proof points, affordability and scholarship information, employability evidence, deadline framing and application guidance. That rarely means translating every page into every language; it means relevance before localisation volume.
Channel mix and discovery. Prospective students in different markets discover institutions through different combinations of AI-assisted research, search, social platforms, comparison sites, agents and personal networks, and the mix keeps shifting; Full Fabric's analysis of higher education marketing trends covers this in depth. A new source market does not automatically respond to the channels, content and follow-up cadence that work in existing ones, so geographic diversification must be matched by channel diversification.
Communications and timing. Response-time expectations, working weeks, holiday calendars and time zones differ. A follow-up cadence tuned to one region can feel neglectful, or spammy, in another.
Applications, documents and payments. Document types, qualification frameworks, references and payment norms vary by market, and payment options in particular can make or break conversion at deposit stage.
Relationships. Agents, partner schools, pathway providers and alumni all need managing per market, with clear expectations and measurable contribution.
Every one of these adds operational load, which points to the real constraint on diversification, and it is usually not ambition.
The technology problem behind market diversification
Diversification multiplies everything: markets, campaigns, events, agents, currencies, document types, intakes and reporting questions. When each of those lives in a different system, a CRM here, an application portal there, spreadsheets for agents, a finance tool for deposits, answering a basic portfolio question such as "which markets generated enrolled students last cycle, from which sources, for which programmes?" turns into a weeks-long reconciliation exercise, and by the time the answer arrives the cycle has moved on.
The measurement discipline described above is therefore, in practice, an infrastructure question: a diversified strategy needs prospect, source, communications, events, application, offer, payment and enrolment data connected around one record per person, segmentable by geography, programme, intake and source. As Full Fabric's guide to managing multi-campus admissions across Europe shows, the limiting factor on complex international operations is usually the connectedness of the data, not the ambition of the plans.
How Full Fabric supports a diversified recruitment strategy
It is worth being precise about what a platform can and cannot contribute here. Full Fabric does not predict which country an institution should target next, does not provide global student-mobility forecasting, and does not replace market research from sources such as the OECD, the British Council or Studyportals. No CRM does, and claims otherwise should be treated sceptically. Market selection remains a strategic judgement built on external evidence and institutional data.
What Full Fabric provides is the operational measurement layer that makes a diversified strategy manageable once markets are chosen. Because it is built on a single data model, with one record per person from first enquiry through application, offer, payment and enrolment, it lets institutions see their own funnel by geography, programme, intake and source. Enquiry capture spans forms, events, agents and campaigns; payments support multiple currencies; and reporting covers cohort analysis, conversion across the full lifecycle and programme and intake performance. Documented capabilities such as the UTM lifecycle attribution report connect campaign, source and medium to progression through lifecycle stages where UTM data is captured. Two qualifications keep expectations accurate. First, this attribution is configuration-dependent: where geography, source and UTM data are captured and configured, institutions can compare lifecycle progression and enrolment outcomes across markets, programmes, intakes and recruitment sources; it is not a complete multi-touch attribution product. Second, cost-per-enrolled-student analysis also requires spend data from advertising, finance or analytics systems, which sits outside the platform.
In portfolio terms, that means an institution can answer the questions this article argues matter most: which markets generate submitted applications rather than just enquiries, which convert from offer to enrolled, where the funnel is slowing, and how the same market performs differently across programmes. For institutions whose existing enterprise systems must stay in place, Full Fabric also operates alongside them through its integrations and connectors. The platform does not guarantee recruitment growth, and it does not make market decisions; it makes those decisions measurable, and measurable decisions are the difference between a diversification strategy and a diversification hope. Broader operational tactics for growing international intake are covered in Full Fabric's strategies for international enrolment growth.
What European universities should do now
A practical sequence for the coming planning cycle:
- Quantify current concentration. From the institution's own data, establish what share of international enrolments and international tuition revenue comes from the top one and top three source markets, overall and by programme.
- Run the shock scenario. Model a 20-30% fall in the largest market, and a deterioration in visa conversion, and identify which programmes and budgets are exposed.
- Classify the portfolio. Assign current and candidate markets to core, growth, test and partnership-led categories, each with an owner, an investment level and success criteria in enrolment terms.
- Fix measurement before expanding. Ensure the full funnel and source attribution are tracked per market and per programme, so that new-market tests can actually be evaluated.
- Launch one or two disciplined tests. Specific programmes, defined audiences, modest budgets, pre-agreed criteria, full-funnel evaluation, and a genuine willingness to stop.
- Reassess every cycle. Treat market viability, affordability, visa conditions and currency effects as variables to review annually, not assumptions to set once.
None of this requires abandoning the markets that built the institution's international community. It requires knowing exactly how dependent the institution is on them, and building measured alternatives before a shock makes the exercise urgent.
Frequently asked questions
Why should European universities diversify international student recruitment?
Because international student flows have become more volatile and more contested. OECD data shows new inflows to OECD countries fell around 13% in 2024, concentrated in the US, UK, Canada and Australia, while other destinations grew. The pattern is redistributing rather than showing a uniform decline, and policy, affordability and competition can shift any single market quickly. Diversification reduces the risk that one shock materially damages an institution's intake or tuition income.
Are China and India still important recruitment markets?
Yes. In 2023, Chinese and Indian students together accounted for roughly one-third of all international students enrolled in OECD countries. Both remain strategically important across international higher education, although their importance varies substantially by institution, programme and destination country. The strategic issue is not their importance but concentration: assuming historical volumes will continue unchanged, from any market, is no longer a safe planning basis.
Which international student markets are growing?
Current evidence points to broadening demand rather than one successor market. British Council analysis shows strong growth in UK student visa issuance from South Asian markets including Bangladesh, Nepal and Pakistan in 2025; Studyportals platform data shows Indonesian study-abroad interest at record levels in early 2026; and institutional surveys show universities targeting Sub-Saharan Africa, Southeast Asia, Latin America and Gulf markets. These are demand signals to validate against an institution's own programmes and data, not a ranking.
What is source-market concentration risk in higher education?
It is an institution's exposure to enrolment or revenue disruption because too large a share of its international pipeline depends on a small number of source countries. It should be measured from the institution's own data, in both headcount and tuition-revenue terms, and stress-tested with scenarios such as a 20-30% fall in the largest market.
How many recruitment markets should a university target?
There is no universal number. Spreading a limited budget across dozens of countries can be worse than focusing on a few, because every market carries fixed operational costs. The better question is whether the portfolio contains enough evidence-backed markets, each with clear programme fit, measurable channels and defined investment, that no single market failure would be destabilising.
How can universities identify new international recruitment markets?
Combine external evidence, such as OECD and Eurostat mobility data, British Council analysis, Studyportals demand data and ICEF sector intelligence, with internal evidence: existing enquiries, applications, current students, alumni and partner relationships. Assess candidates across demand, conversion, programme fit, affordability, visa environment, competition, infrastructure and operational readiness, at the level of market × programme × intake.
How should universities test a new source market?
With a controlled, time-boxed experiment: one or two programmes, a defined audience, a modest budget, one or two measurable channels and one intake, with success criteria set in advance in enrolment terms. Evaluate the test through the full funnel, from application through offer, acceptance, deposit and enrolment, then scale only if the evidence supports it, and stop if it does not.
What metrics should universities use to compare recruitment markets?
Full-funnel metrics per market and per programme: enquiries, applications started and submitted, offers, acceptances, deposits and enrolments; stage-to-stage conversion rates; acquisition cost per enrolled student; yield and revenue; time to conversion; and withdrawal, deferral and visa-related attrition. Lead volume alone is misleading, and external signals such as search interest should inform hypotheses, not budgets.
Is international student mobility declining?
Not in a simple global sense. New international tertiary student inflows to OECD countries fell 13% in 2024, but the decline was concentrated in the four largest destinations while flows to other OECD destinations grew by 5%. The evidence points to redistribution and uneven growth across destinations, alongside regional and transnational alternatives, rather than a universal collapse in international demand.
How can CRM data support international recruitment diversification?
By making the portfolio measurable. When enquiries, sources, campaigns, events, applications, offers, payments and enrolments are connected around one record per person, institutions can compare markets on enrolment outcomes rather than lead volume, attribute results to specific channels and agents, spot where funnels slow, and evaluate market tests honestly. A CRM does not choose markets, but it determines whether market decisions can be evidence-based.
Related Full Fabric reading
- The Ultimate University Student Recruitment Plan
- 6 Strategies for International Enrolment Growth
- How Universities Can Utilise Alumni Relations to Promote International Student Recruitment
- What Are Prospective International Students Prioritising Right Now?
- Higher Education Marketing Trends to Watch
- Managing Multi-Campus Admissions Across Europe
- Higher Education CRM Platform
Further reading and sources
International student mobility
- OECD, International Students in Higher Education (April 2026)
- OECD, International Migration Outlook 2025
- OECD, Education at a Glance 2025, tertiary mobility indicators
Recruitment market intelligence
- British Council, Five Trends to Watch in 2026
- British Council, US international student slump providing opportunities for UK universities (March 2026)
- British Council, Student mobility and TNE overview: HESA 2024/25 and UKVI 2025 data
- HESA, UK higher education student numbers fall for second year in a row (January 2026)
- Studyportals, Why 40% of universities are diversifying markets right now
- Studyportals, The growing significance of Indonesia as a student recruitment market (May 2026)
- ICEF Monitor, From the Big Four to the Big Fourteen (January 2026)
- ICEF Monitor, Agent Voice 2026 survey findings
Full Fabric resources

